Ask about Vietnam stock market valuation and you will get a single number back — an index P/E, quoted with confidence, usually followed by the word “cheap”. It is the most repeated claim about this market and the least examined.
The number is not wrong. It is just far less informative than it appears, for reasons specific to how this market is built: one sector dominates the index, several large sectors are cyclical, and a meaningful share of the market capitalisation cannot be bought by a foreign investor at all.
This piece deliberately does not print a current multiple. Any figure published here would be stale within weeks, and the useful thing is not the number — it is knowing which four questions make the number mean something.
How do you assess Vietnam stock market valuation properly?
Short answer: Use four lenses rather than one — index P/E, index P/B, earnings yield against the local deposit rate, and market cap to GDP. Then adjust for structure: the headline multiple is dominated by banking, cyclical earnings distort single-year figures, and the investable float is smaller than total market capitalisation because of state holdings and foreign ownership caps.
Four lenses, none sufficient alone
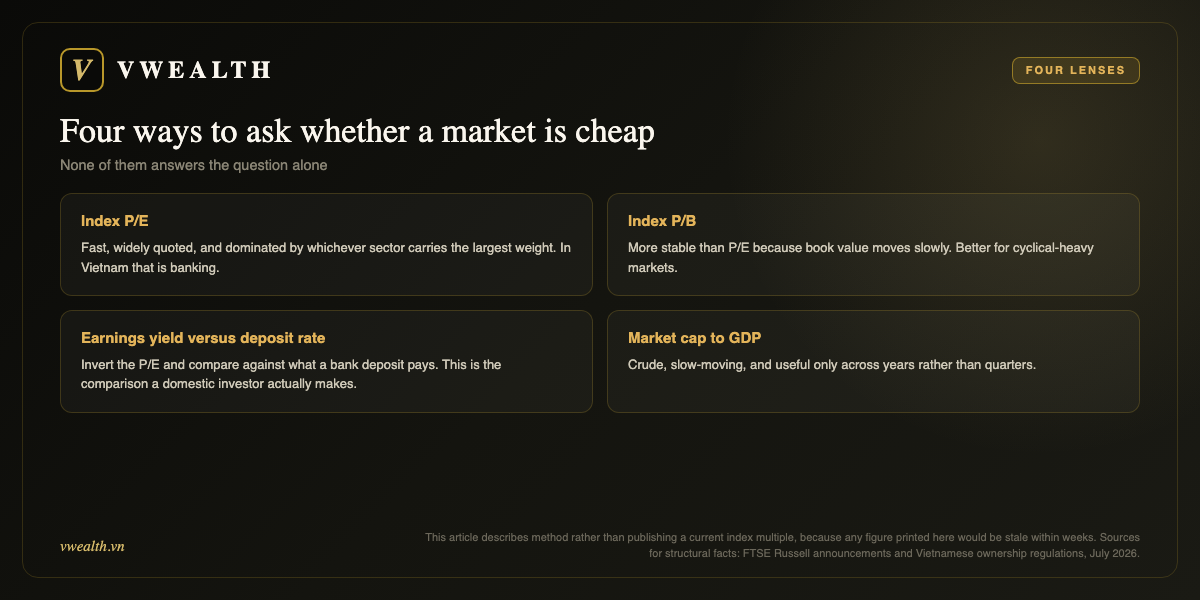
Index P/E
The one everybody quotes. Fast to obtain and heavily influenced by whichever sector carries the largest weight.
Its weakness in Vietnam is severe: banking dominates, so the headline figure is largely a bank multiple wearing a market label.
Index P/B
Price against book value. More stable, because book value does not swing the way a single year of earnings does.
For a market with heavy cyclical representation, this is often the more honest lens. It is also the standard tool for banks, which makes it doubly appropriate here.
Earnings yield versus the deposit rate
Invert the P/E to get an earnings yield, then compare against what a local bank deposit pays.
This is the comparison a domestic investor actually makes, and foreign commentary almost never includes it. If a deposit pays close to what the market yields in earnings, equities are not obviously cheap to the people who set the marginal price.
Market cap to GDP
Crude and slow. Useful across years, useless across quarters. Worth knowing the direction of travel, not the level.
Four structural facts that distort any single number
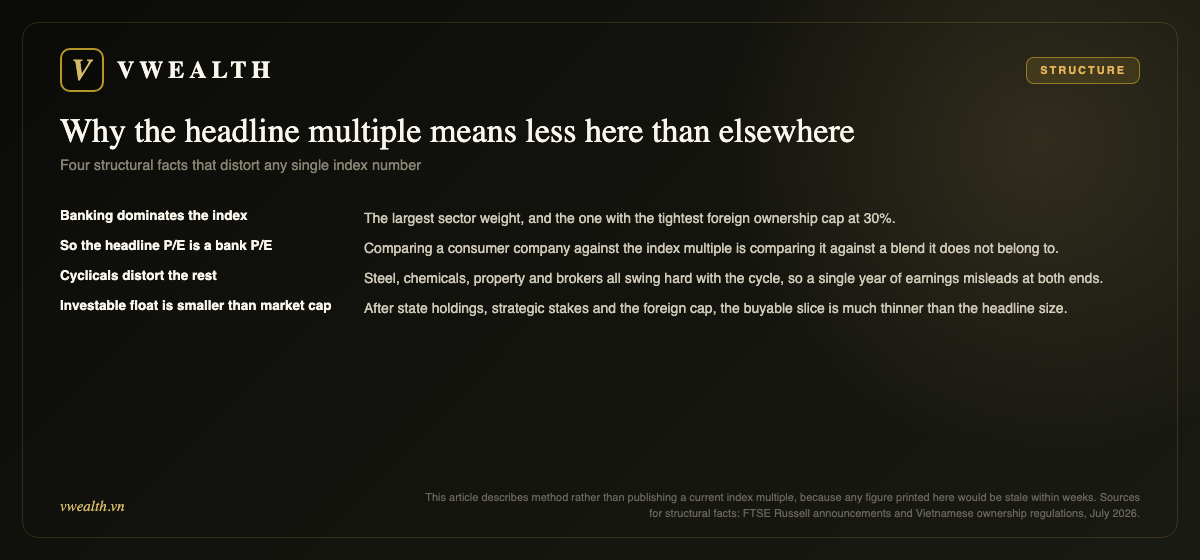
Banking dominates the index
It is the largest sector weight and it is also the sector with the tightest foreign ownership constraint — a 30% aggregate cap for ordinary commercial banks, with an exception permitting up to 49% for banks receiving mandatory transfers as part of restructuring, where the state does not hold control.
Two consequences. The headline multiple is a bank multiple. And a large part of the sector’s market capitalisation is unavailable to foreign buyers.
Cyclicals distort single-year earnings
Steel, chemicals, fertiliser, property and securities firms all have earnings that swing hard with the cycle.
At a cyclical peak, earnings are unusually high, the denominator inflates, and P/E prints low — precisely when the risk is greatest. At a trough the reverse happens. Our piece on steel and industrials works through this in the sector where it bites hardest.
Investable float is smaller than market cap
After removing state holdings, strategic stakes and anything above the foreign ownership cap, the slice a foreign investor can actually buy is considerably thinner than the headline market size.
This is not a theoretical point. It is the reason Vietnam’s weight in the global index baskets is small — roughly 0.22% of FTSE Emerging and 0.34% of FTSE Emerging All Cap on FTSE Russell’s own estimates at the April 2026 review, despite the size of the economy.
Comparisons against the wrong peer set
Comparing a Vietnamese multiple against a developed market tells you almost nothing, because the discount reflects liquidity, access constraints, currency and disclosure differences rather than a mispricing.
The honest comparison is against markets in the same classification with similar access constraints.
Four questions before calling it cheap
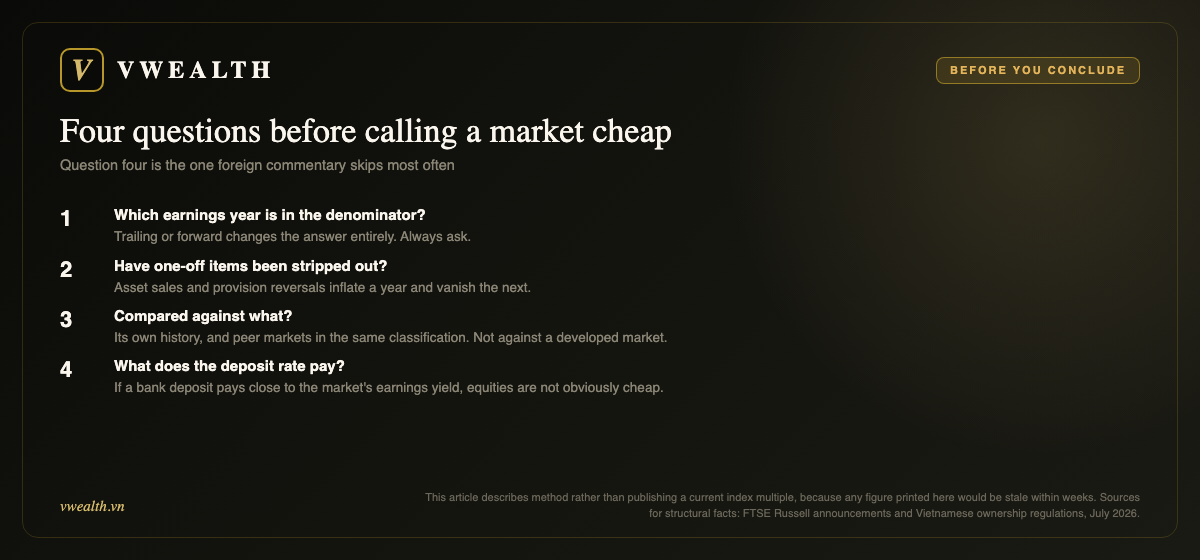
1. Which earnings year is in the denominator?
Trailing earnings are actual and verifiable. Forward earnings are a forecast and typically make the market look cheaper.
Both are legitimate; conflating them is not. Always establish which one a quoted figure uses.
2. Have one-off items been stripped out?
Asset disposals, revaluations and provision reversals inflate a year of earnings and disappear the next. At index level these wash out somewhat, but in a market where such items are common they can shift the aggregate meaningfully.
3. Compared against what?
Two valid comparisons: the market against its own history, and the market against peers in the same classification. Everything else invites false conclusions.
4. What does a bank deposit pay?
The question foreign analysis omits most consistently, and the one domestic investors weigh most heavily.
If deposits pay a rate close to the market’s earnings yield, then equities carry extra risk for little extra reward, and the marginal domestic buyer has a good reason to stay in cash. That dynamic sets the price regardless of what looks cheap on a cross-border screen.
What the upgrade does and does not change
Since the reclassification is the dominant story right now, it is worth separating its effect on valuation from the noise around it.
What it changes. Access. The removal of the prefunding requirement for foreign institutions was the condition FTSE Russell named explicitly, and it removes a hard block that kept certain mandates out of the market entirely.
What it adds. A defined quantity of passive demand, proportional to the index weight, arriving in tranches into 2027.
What it does not change. Earnings. Foreign ownership caps. The composition of the index. The deposit rate. In other words, three of the four lenses above are untouched by it.
The implication is worth stating plainly: an upgrade can raise the price without changing the value, and that is precisely what a re-rating is. Whether the new level is justified depends on the same four questions as before. Full detail in what actually changes in September.
Building the assessment yourself, step by step
Since the article does not hand you a number, here is how to produce one you can defend.
Step 1 — collect the raw inputs
Current index level and trailing index earnings, from the exchange or a data provider. Index book value. The prevailing twelve-month deposit rate at a large local bank. Nominal GDP for the most recent full year.
That is four numbers, all publicly available, and all dated. Write the date next to each.
Step 2 — compute the four lenses
P/E from index level and earnings. P/B from index level and book value. Earnings yield as the inverse of P/E. Market cap to GDP as total market capitalisation divided by nominal GDP.
None of this requires modelling. It is arithmetic on four public inputs.
Step 3 — compare against the market’s own history
Pull the same figures for the same month in each of the past five years. This single step converts a meaningless absolute number into a range you can position against.
It also reveals something useful: how much of the current level is explained by earnings changing versus price changing.
Step 4 — apply the structural adjustments
Ask what proportion of index earnings comes from banks, and what proportion comes from cyclical sectors at an unusual point in their cycle. If those two together dominate, treat the P/E as indicative only and lean on P/B.
Step 5 — write down your conclusion in one sentence
With the date. Something like: “On trailing earnings as of this month, the market sits in the lower half of its own five-year range, with the caveat that bank earnings drive the aggregate.”
A sentence like that survives contact with reality. “Vietnam is cheap” does not.
What a discount is actually paying you for
Discounts exist for reasons, and it helps to name them rather than treat the gap as free money.
Liquidity. Positions take longer to build and longer to exit. That is a real cost and it deserves a discount.
Access constraints. The trading code, the capital account, the ownership caps. Each adds friction, and friction is priced.
Currency. A managed currency introduces a risk that a floating one distributes differently. Foreign investors price that.
Disclosure and accounting. Vietnamese accounting standards differ from IFRS, which raises the analytical burden for a foreign analyst. Our piece on reading Vietnamese financial statements covers the practical differences.
Governance. Ownership structures are often concentrated, and minority protections differ from developed-market norms. See corporate governance in Vietnam.
The investment question is not whether a discount exists. It is whether the discount is larger than these five factors justify — and whether any of them are narrowing.
On that last point, one is measurably narrowing: access. The prefunding removal is a concrete reduction in friction, and it is the strongest argument that some portion of the historical discount is less justified than it was.
What would make this market genuinely expensive
A useful discipline is to define in advance what would change your mind, so the answer is not decided by whatever the price did last quarter.
Earnings yield falling below the deposit rate. At that point the domestic marginal buyer has a straightforward reason to prefer cash, and equities need growth to justify themselves.
Cyclical sectors printing peak earnings while multiples stay low. The classic trap: the market looks cheapest exactly when the earnings base is least sustainable.
Multiples expanding without earnings following. A re-rating on flow rather than fundamentals. Sustainable only while the flow continues.
The discount to peers closing entirely. The structural reasons for it have not disappeared, so a fully closed discount implies the market has priced away compensation for real constraints.
None of these are predictions. They are tripwires, and having them written down in advance is worth more than any current multiple.
Three mistakes in valuing this market
Treating the index multiple as a stock-level benchmark
The index blend is dominated by one sector. A consumer or technology company should be compared against its own sector and its own history, not against a bank-weighted average.
Ignoring the currency
A foreign investor’s return is in dollars, and the dong does not float freely. A market that looks cheap in local terms can deliver a poor outcome in dollars. Covered in what the dong means for USD returns.
Assuming the discount should close
Vietnam trades at a discount to more developed markets for structural reasons — access constraints, disclosure differences, liquidity. Those reasons narrow gradually if at all. Buying on the assumption that a structural discount is a temporary mispricing is a long wait.
Sector-level valuation: where the index number breaks down completely
Once you accept that the index multiple is a blend, the natural next step is to value sectors separately. Each behaves differently enough that the same tool does not work across all of them.
Banks
Value on P/B alongside return on equity, not on P/E alone. A bank earning a high return on equity deserves a higher multiple of book, and that relationship is more stable than earnings-based comparisons.
Then adjust for asset quality, which is the variable that separates banks and the hardest to read from the outside. Detail in our banking sector guide.
Property
Revenue is recognised on handover, so a year of earnings reflects sales made two or three years earlier. P/E is close to meaningless in isolation.
What to read instead: inventory, customer advances — cash collected but not yet recognised as revenue, which indicates future earnings — and the debt position. See how the sector really works.
Consumer and retail
The sector where P/E works most straightforwardly, because earnings are relatively steady and the business model is easy to model.
The sector-specific measure worth adding is same-store sales growth, which separates growth from adding outlets. Covered in the retail sector piece.
Cyclicals
Use P/B, or P/E computed on an average of several years’ earnings rather than the most recent one. Judging a cyclical on one year of earnings is the single most reliable way to buy at a peak.
Securities firms
Earnings track market turnover, which makes them a leveraged bet on market activity rather than an independent business cycle. Their multiples expand and contract with sentiment faster than almost anything else listed.
Putting a number on it responsibly
If you do want a single figure to work with, the defensible version has three parts rather than one.
The level — computed from current inputs with the date attached.
The position — where that level sits within the market’s own five-year range.
The caveat — which sector is driving the aggregate, and whether its earnings are at an unusual point.
Stated together, that is a defensible view. Stated as “the market trades at X times earnings”, it is a fact with no meaning attached.
How valuation and flow interact
The two are usually discussed separately and they are not separate, particularly in a market this size.
In a deep market, flow is small relative to float and valuation is set by fundamentals. In a market where the investable float is thin, flow itself moves the multiple — meaning price can detach from earnings for extended periods simply because buying pressure exceeds available supply.
Vietnam sits closer to the second case than most investors assume, because of the float arithmetic described earlier. Remove state holdings, strategic stakes and capped foreign room, and the tradeable slice is thinner than the headline market size suggests.
What this means practically
Multiples can expand without earnings improving. That is not evidence of mispricing being corrected; it is evidence of demand meeting constrained supply.
And they can contract just as fast. Thin float works in both directions, which is why newly included markets often see sharper drawdowns when flows reverse.
So valuation discipline matters more, not less. In a market where flow can carry the price, having written down what you consider fair value in advance is the only thing that prevents you from rationalising a level after the fact.
A note on time horizon
Everything above assumes you are asking whether to own this market for years rather than weeks. For a shorter horizon, valuation is close to irrelevant — flow, positioning and sentiment dominate over months.
That is not a criticism of shorter horizons. It is a reminder that the four lenses answer one specific question: is the price reasonable relative to what the underlying businesses earn.
They do not answer whether the price goes up next quarter, and no valuation framework ever has.
Common claims, examined
Four statements you will encounter repeatedly, and what each is actually saying.
“Vietnam trades at a discount to the region”
Usually true, and usually presented as an opportunity. It is more accurately a price for liquidity, access friction, currency management and disclosure differences. The question is whether the discount exceeds what those factors warrant.
“Earnings growth will close the gap”
This conflates two separate things. Earnings growth raises the numerator of value; closing a valuation gap requires the multiple to expand. Both can happen, but they are different claims with different drivers.
“The upgrade will re-rate the market”
It may raise prices through flow. Re-rating means paying more for the same earnings, which is a change in what investors are willing to pay rather than a change in what they receive. Worth being precise about which is being predicted.
“Valuations are at multi-year lows”
Check the denominator before accepting this. A low multiple during a cyclical earnings peak and a low multiple during a genuine price decline are opposite situations that produce the same headline.
Each of these can be true. None of them is self-evident, and all four are usually stated as though they were.
Frequently asked questions
Why does this article not give a current P/E?
Because a number printed today is stale within weeks and readers arrive at articles months later. The method survives; the figure does not. Current index multiples are published by the exchanges and by data providers.
Is Vietnam cheaper than its regional peers?
It usually trades at a discount to more developed regional markets, and the reasons are structural rather than a mispricing to be arbitraged. Whether the discount is wider or narrower than usual at any moment requires current data.
Which lens matters most?
For a market this cyclical, P/B and the earnings-yield-versus-deposit comparison usually carry more information than the headline P/E.
Does the foreign premium affect valuation?
Yes, for a foreign buyer. In capped names, foreign-to-foreign trades often clear above the on-screen price, so the effective entry multiple is higher than the published one. See foreign room and the cap that blocks foreign money.
Does an index upgrade justify a higher multiple permanently?
Partly. Lower access friction is a genuine reduction in one component of the historical discount, and that argument survives after the flow stops. The passive demand itself does not — it arrives once, in tranches, and then it is done.
How often should this be reassessed?
Quarterly, when earnings update the denominator. Reassessing between reporting seasons mostly measures price movement rather than value.
Summary
Judging Vietnam stock market valuation from a single index multiple produces a confident answer to a question that was never properly asked.
Four lenses, then four adjustments for structure: banking dominance, cyclical earnings, investable float smaller than market capitalisation, and the right peer set. Then the question domestic investors actually weigh — what a deposit pays.
The upgrade changes access and adds a bounded quantity of passive demand. It does not change earnings, caps, index composition or the deposit rate. Which means the valuation question after September is the same one as before, asked at a different price.
Further reading: the complete guide to the Vietnamese market, the banking sector for foreign investors, and reading Vietnamese financial statements.
This article is for information and education. It is not a recommendation to buy, sell or hold any security. Structural facts are as of July 2026.


