Every piece written about the Vietnam stock market outlook arrives at the same destination: a number for where the index will be in twelve months. The numbers differ, the reasoning rarely does, and almost none of them are revisited when the year ends.
This article does not contain a target. Not out of caution, but because a target is the least useful output of the work — it compresses a set of conditional judgements into a single figure that cannot be acted on and cannot be checked.
What follows instead is a method: four observable inputs, the order in which a cycle actually turns, and what to write down in place of a forecast so that you can tell later whether you were right.
How should you read the Vietnam stock market outlook?
Short answer: By tracking four published indicators — market turnover, earnings revisions, foreign flow and credit conditions — rather than by adopting someone’s index target. Then writing three conditional scenarios with observable triggers, and a review date. A forecast you cannot check is not a view; it is a guess with a decimal point.
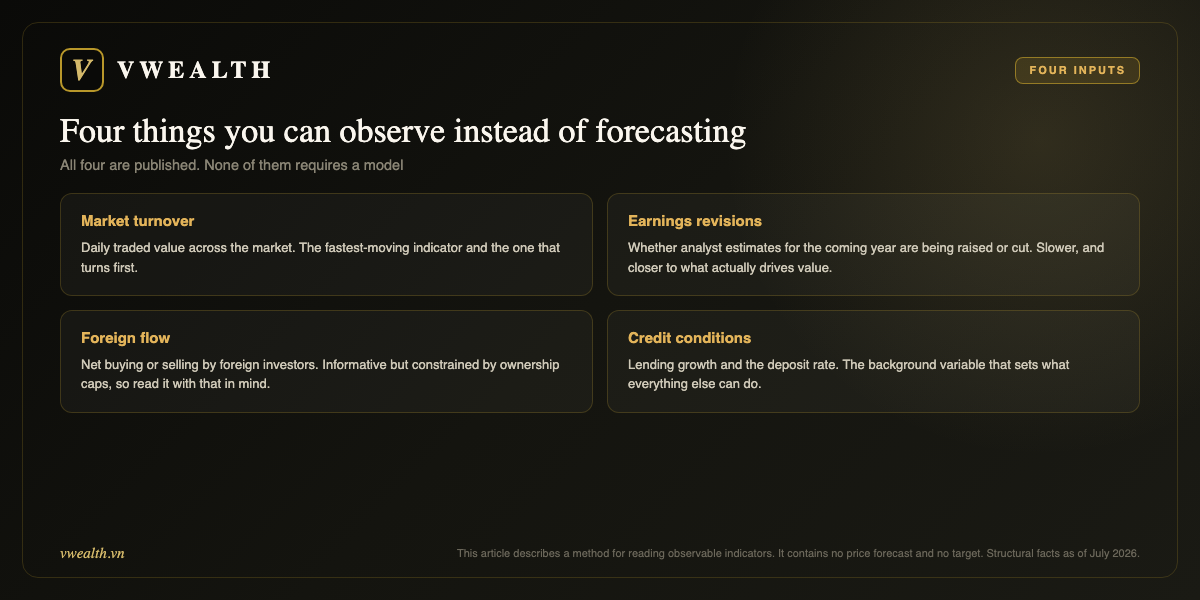
Four inputs you can observe
Market turnover
Total daily traded value across the market. The fastest-moving of the four and the one that changes first.
Turnover rising sustainably over weeks indicates money entering. Turnover collapsing indicates the opposite, and it usually happens before prices reflect it fully.
What it does not tell you is why. A rise driven by domestic retail participation and one driven by institutional allocation look identical in the turnover figure and mean very different things about durability.
Earnings revisions
Whether estimates for the coming year are being raised or lowered.
Slower than turnover, and much closer to what determines value. A market where earnings estimates are being cut while prices rise is a market re-rating on flow rather than on fundamentals — which can continue, and is worth naming for what it is.
The practical version for an individual investor: track the direction of revisions for the largest sectors rather than for the whole index. In Vietnam that means banking above all, since it carries the largest weight.
Foreign flow
Net buying and selling by foreign investors, published daily.
Read it with one caveat specific to this market: foreign buying is capped in many of the largest names. Sustained foreign selling can therefore be a signal, while sustained foreign buying is partly a function of what is available to buy. The mechanics are in foreign room and the cap that blocks foreign money.
Credit conditions
Lending growth and the prevailing deposit rate. The background variable that sets the range within which everything else operates.
A high deposit rate competes directly with equities for domestic savings — and domestic savers are the marginal price setter in this market far more than foreign institutions are. This is the input foreign analysis consistently underweights.
The order in which a cycle turns
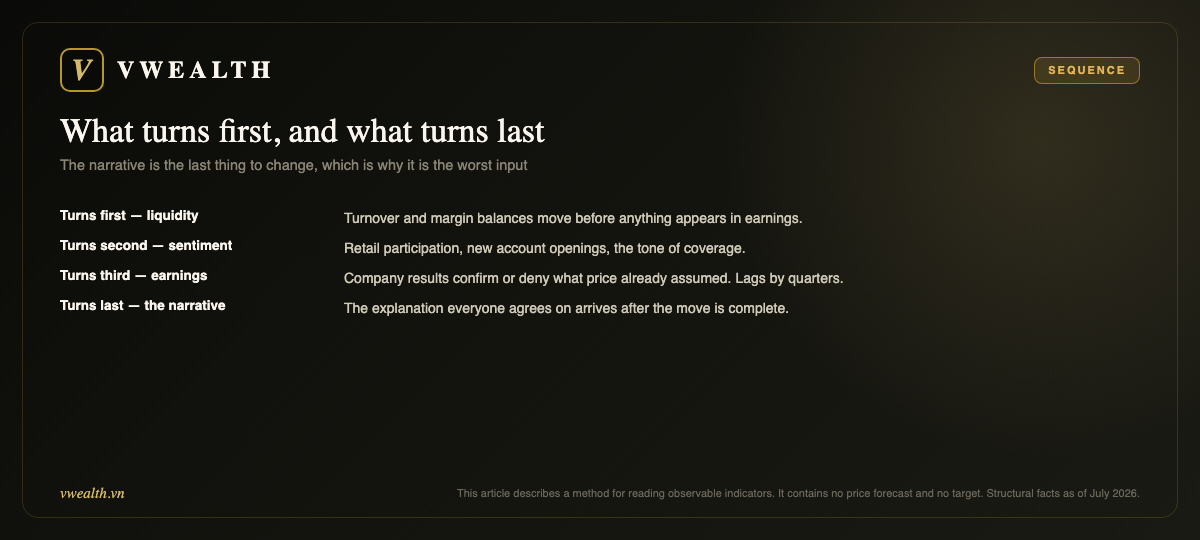
The sequence matters more than any individual reading, because it tells you which signals are early and which are confirmation.
Liquidity turns first
Turnover and margin lending move before earnings show anything. Money arrives or leaves, and prices respond, well before the reason becomes visible in company results.
Sentiment turns second
Retail participation, new account openings, the tone of commentary. Observable, and by the time it is obvious the first move has usually happened.
Earnings turn third
Results confirm or contradict what prices already assumed, with a lag measured in quarters. This is why a market can look expensive on trailing earnings at the start of an upturn and cheap at the start of a downturn.
The narrative turns last
The agreed explanation for what happened arrives after the move is complete. Which makes consensus commentary the worst available input for a forward view, despite being the most abundant.
The practical implication: if you find yourself agreeing with an explanation that everyone already accepts, you are reading a description of the past.
What to write instead of a forecast
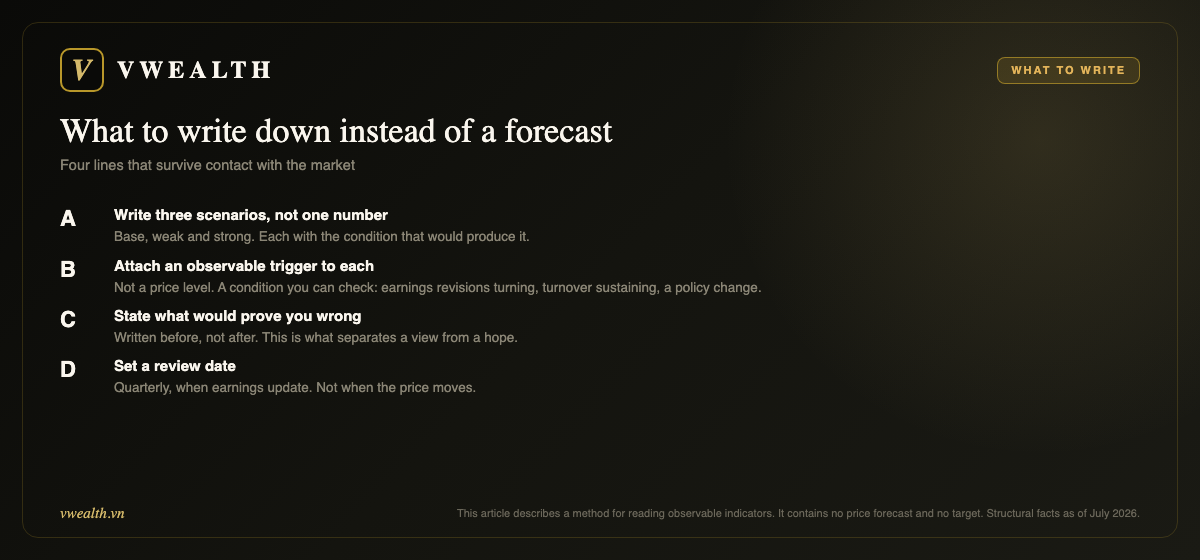
A. Three scenarios, not one number
Base, weak and strong — each stated as a condition rather than as a level. “Earnings revisions stabilise and turnover holds” is a scenario. “Index reaches X” is a wish with arithmetic attached.
B. An observable trigger for each
Something you can check in published data. Revisions turning positive for two consecutive months. Turnover sustaining above a level for a quarter. A change in the deposit rate.
Not a price level — price is the thing being predicted, so using it as a trigger is circular.
C. What would prove you wrong
Written before, not after. This single line does more for the quality of a view than any amount of analysis, because it forces the view to be falsifiable.
D. A review date
Quarterly, when earnings update the inputs. Reviewing when the price moves means reviewing on noise, and it produces the pattern where a view changes exactly as often as the market does.
Reading each input in practice
The inputs are only useful with a method for reading them. Here is what to actually do with each.
Turnover: read the trend, not the day
A single session tells you nothing. What matters is the twenty-session average against the same figure three and six months ago.
Two patterns are worth naming. Rising turnover with rising prices indicates money entering, and it is the more durable configuration. Rising turnover with falling prices indicates distribution — someone is selling into demand — and it frequently precedes weakness.
The reverse also applies: falling turnover during a decline often signals exhaustion rather than continuation, because the selling has run out of participants.
Earnings revisions: read the direction and the breadth
Direction is whether estimates are being raised or cut. Breadth is how many sectors are moving the same way.
A market where one sector is being upgraded and five downgraded is not the same as a broad-based improvement, even if the aggregate index estimate rises. Breadth is the more reliable of the two.
Foreign flow: read it relative to available room
The caveat mentioned earlier deserves a method. Persistent foreign selling in a name with plenty of available room is a clean signal — they could buy and are choosing not to.
Persistent foreign buying in a name near its cap tells you very little, because the constraint rather than the conviction may be setting the pace.
Credit conditions: read the spread
The single most useful derived number is the gap between the market’s earnings yield and the twelve-month deposit rate.
When that gap is wide, equities compensate meaningfully for their additional risk. When it narrows toward zero, the domestic saver has a rational reason to stay in the bank — and domestic savers set the marginal price here.
Tracking that spread quarterly gives you more information than any commentary about sentiment.
A worked example of the scenario format
Written the way we would actually keep it, so the shape is clear. These are illustrative conditions, not our view.
Base case. Condition: earnings revisions flat to slightly positive, turnover holding around its recent average, deposit rate unchanged. Consequence: the market trades within its recent valuation range, with index flow providing modest support around inclusion dates. Trigger to confirm: two consecutive months of stable revisions.
Weak case. Condition: earnings revisions turning negative across more than two major sectors, or a material rise in the deposit rate. Consequence: multiple compression regardless of index flow, because the domestic alternative improves. Trigger: revision breadth deteriorating for two months, or a policy rate change.
Strong case. Condition: revisions rising with breadth, turnover sustaining above its average for a full quarter, foreign selling ceasing in names with available room. Consequence: re-rating with earnings support rather than on flow alone. Trigger: all three conditions present simultaneously.
What would prove the whole framework wrong. If prices move substantially with none of the four inputs changing, then something is driving this market that the framework does not capture — and the correct response is to find out what, not to adjust the scenarios.
Review date. After the next quarterly reporting season.
Why this format is worth the effort
Because in three months you can look at it and establish, without ambiguity, whether you were right and why.
A forecast of an index level cannot do that. If the index ends up near the number, you do not learn whether the reasoning was sound or the errors cancelled. If it ends up far away, you do not learn which input you misjudged.
What this framework does not cover
Three things it deliberately excludes, so the limits are explicit.
Individual companies. The cycle view tells you about the environment. It says nothing about whether a specific business is gaining or losing share, and company work cannot be skipped by getting the macro right.
Shocks. Policy changes, regional events, currency crises. No framework built on trailing indicators anticipates a discontinuity, which is the argument for position sizing rather than for a better framework.
Timing. The sequence tells you the order in which things turn, not the interval between them. Liquidity can lead earnings by one quarter or by four, and nothing in the observable data distinguishes those cases in advance.
What is specifically knowable right now
Rather than speculate, here is what is settled and dated as of writing.
The index reclassification. FTSE Russell moves Vietnam to Secondary Emerging effective 21 September 2026, confirmed at the interim review published 7 April 2026, with inclusion phased into 2027.
The weight. FTSE estimated Vietnam at roughly 0.22% of FTSE Emerging and 0.34% of FTSE Emerging All Cap at that review. That bounds the passive flow arithmetic.
The access change. The prefunding requirement for foreign institutions has been removed — the condition FTSE named explicitly. This is structural and does not expire.
The remaining unknown. The official constituent list, expected in August 2026. That is the only genuinely new information between now and September.
Everything else being written about the coming months is inference layered on those four facts. Full detail in what actually changes in September.
Three ways outlook pieces go wrong
Treating the upgrade as the whole story
It is one input among four, and it affects flow rather than earnings. A view that rests entirely on index inclusion has no answer for what happens after the tranches complete in 2027.
Importing a developed-market framework
Valuation comparisons against developed markets, or assumptions about how quickly information moves into prices, translate poorly to a market where a large share of capitalisation cannot be bought by foreigners and where domestic retail is the dominant participant.
Confusing a scenario with a probability
Writing three scenarios is useful. Assigning them percentages that sum to one hundred is usually false precision — the numbers are made up and they invite the reader to weight them as though they were measured.
Who the marginal buyer is, and why it matters
Most outlook pieces written for a foreign audience assume foreign flow sets the price. In Vietnam that assumption is weak, and correcting it changes what you watch.
Domestic retail dominates participation
Individual domestic investors account for a large share of daily turnover. That has three consequences a foreign reader should carry.
The deposit rate matters more than global rates. The alternative a domestic saver weighs is a Vietnamese bank deposit, not a treasury bond in another currency.
Sentiment moves faster. A participant base weighted toward individuals reacts more quickly and more completely than one weighted toward institutions with mandates and committees.
Margin lending amplifies both directions. Where retail participation is high and leverage is available, moves extend further than fundamentals justify — up and down.
Foreign flow is constrained, not decisive
Even after the reclassification, the passive money involved is bounded by a weight of roughly a fifth to a third of one percent of the relevant baskets, phased over more than a year.
Foreign flow can matter a great deal for a specific stock with available room. It rarely sets the level of the market.
What this changes about the four inputs
It moves credit conditions up the list. If you were only going to track one thing, the spread between the market’s earnings yield and the deposit rate would be a defensible choice — because it describes the decision the marginal buyer is actually making.
Using the framework at different horizons
For a multi-year holder. Only earnings revisions and credit conditions matter. Turnover and flow are noise at that horizon, and reacting to them converts a long-term position into a short-term one by accident.
For a one-to-two-year horizon. All four, reviewed quarterly. This is the horizon the framework is built for.
For anything shorter. The framework does not help. Over weeks, price is driven by positioning and flow in ways trailing indicators do not capture, and pretending otherwise produces false confidence.
Being explicit about horizon before applying any framework prevents the most common error in this area: using a tool designed for one timescale to make decisions on another.
Common outlook claims, translated
Four statements you will meet repeatedly this year, and what each actually asserts.
“Foreign money is coming”
Translated: passive funds tracking FTSE emerging indices will buy an amount proportional to a weight of roughly a fifth to a third of one percent, in tranches, into 2027. The claim is true and the scale is smaller than the phrasing implies.
“Valuations are attractive relative to the region”
Translated: the market trades at a discount, for reasons including liquidity, access constraints and currency. The claim is usually accurate; whether the discount is wider than those factors justify is a separate question the statement does not address.
“Earnings growth will drive the market”
Translated: the speaker expects revisions to turn positive. That is checkable. Ask which sectors and over what period, and the claim becomes either specific or empty.
“Retail participation is at record levels”
Translated: turnover and account openings are elevated. Presented as bullish, it is more accurately a statement about volatility — a market with high retail participation moves further in both directions.
None of these are wrong. They are compressed, and decompressing them is most of the analytical work.
A note on reading research
Broker research in this market is abundant and mostly published in Vietnamese, which creates an asymmetry worth naming.
A foreign investor reading only English-language commentary is reading a summary of a summary, usually written for a different audience with different constraints. The primary material — company filings, exchange disclosures, local analyst notes — is where the information actually is.
Two practical responses. Read the primary sources that are available in English: exchange disclosures, company annual reports where an English version exists, and index provider announcements. And treat English-language market commentary as a starting point rather than an input.
Our piece on reading Vietnamese financial statements covers the accounting differences that make company filings harder to read than they first appear.
Keeping the record
The framework only compounds if you write it down, and the format matters less than the habit.
One page per quarter. The four inputs with their current readings and the direction since last quarter. The three scenarios, unchanged unless a trigger fired. What would prove you wrong. The date.
What to look at when you reopen it. Not whether the market went up. Whether the input you identified as decisive actually moved, and whether it moved in the direction you expected.
After four quarters you have something rare: evidence about which of the four inputs you read well and which you read badly. That is worth more than any single correct call, because it tells you where to add weight next time.
Most investors never build this record, which is why most investors have opinions about markets that do not improve over time. The record is the improvement mechanism.
Frequently asked questions
Why no index target?
Because a target cannot be acted on without also knowing the timeframe and the path, and it cannot be checked in a way that improves the next forecast. The scenario format can be checked.
Which of the four inputs matters most?
Credit conditions set the range and earnings revisions determine the durability. Turnover is the fastest but also the noisiest.
Where do I find these numbers?
Turnover and foreign flow are published daily by the exchanges. Earnings revisions require a data provider or aggregating broker research. Deposit rates are published by the banks themselves.
How often should the view be updated?
Quarterly. Updating monthly means responding to noise; updating annually means missing the turn.
Does technical analysis help here?
It answers a different question — about price behaviour rather than about the cycle. Whether that is useful depends on your holding period, and it is not a substitute for the four inputs above.
What about macro forecasts?
GDP and export figures are widely reported and only loosely connected to equity returns over any period short of a decade. Credit conditions are the macro variable with the most direct link to this market.
Summary
A useful Vietnam stock market outlook is not a number. It is four observable inputs, an understanding that liquidity turns before earnings and narrative turns last, and three conditional scenarios with triggers you can check.
What is genuinely knowable right now is narrow and dated: the reclassification takes effect on 21 September 2026, the weight is small, the access change is structural, and the constituent list arrives in August.
Everything beyond that is inference — which is fine, provided it is labelled as such and written in a form that can be proved wrong.
Further reading: how to tell if the market is actually cheap, an honest assessment of the risks, and the complete guide to the market.
This article is for information and education. It contains no forecast, target or recommendation. Structural facts are as of July 2026.


